Home › Articles › Prepare Your Home for an Appraisal
To prepare for a home appraisal, make the whole house accessible, turn on all utilities, fix safety defects such as missing handrails, exposed wiring and peeling paint, tidy and clean, and give the appraiser a written list of improvements with dates, permits and any ground rent or HOA information. Preparation will not change the market, but it ensures the appraiser sees everything accurately and prevents avoidable delays.
Homeowners often ask me whether they should repaint, rent a dumpster or stage the living room before the appraiser comes. The honest answer is that some preparation helps a great deal and some is wasted effort. This checklist separates the two.
Since September 1989, I have walked through thousands of Baltimore-area homes, from Dundalk rowhouses to Roland Park colonials to Carroll County farmhouses. I can tell you what I notice, what I do not, and what makes a visit smooth.
First, a reality check. An appraisal reflects the market, not the seller's effort. I value your home by analyzing recent sales of similar properties and adjusting for differences, including condition. Fresh staging will not add a price tag. What preparation can do is make sure I see the true condition, count every feature, and avoid delays. That is worth doing.
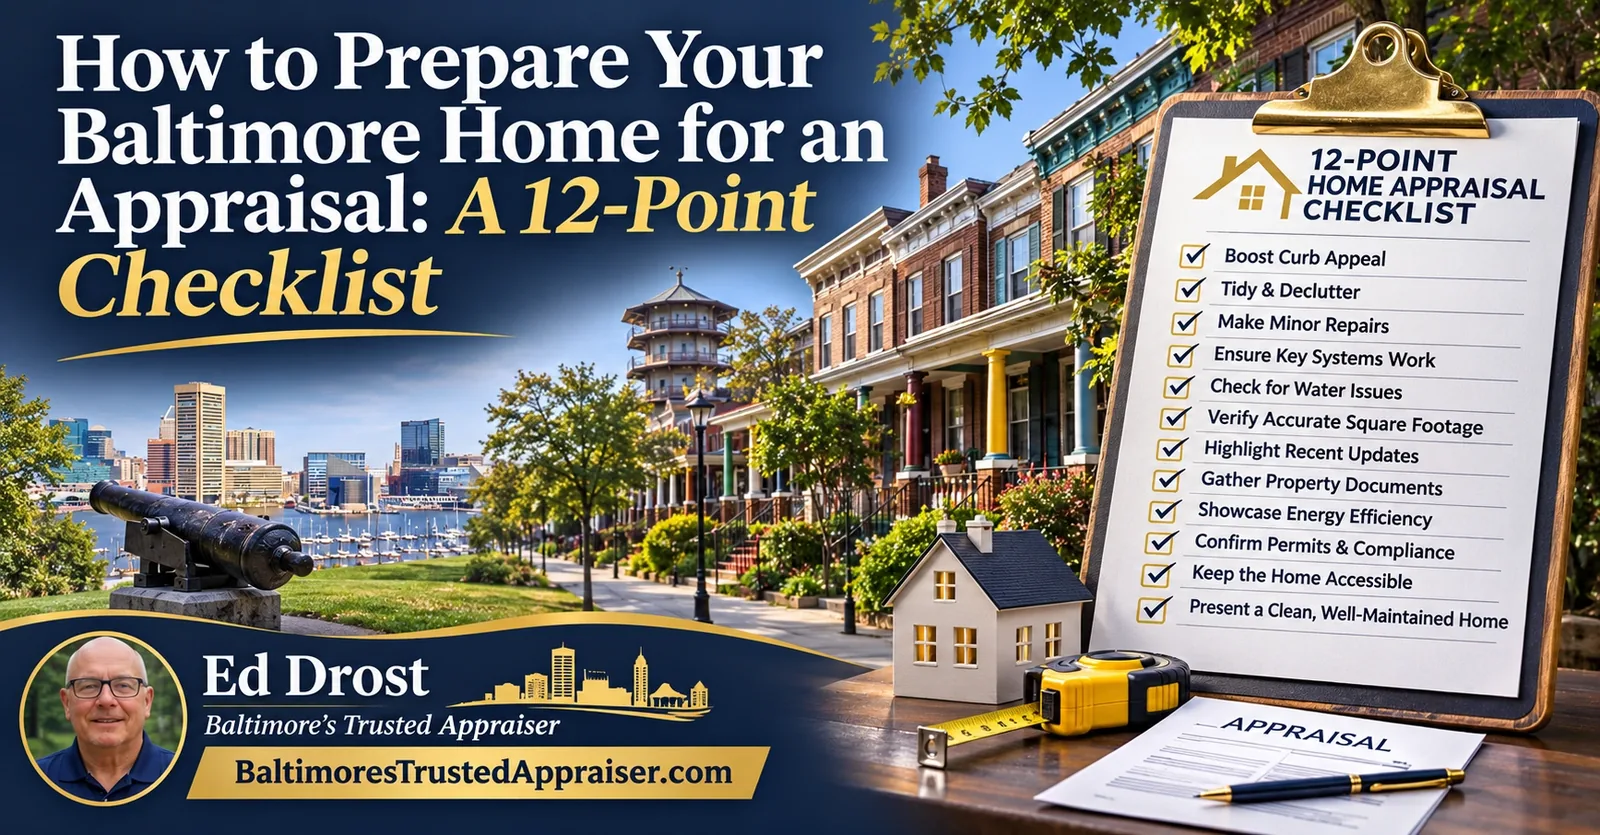
What are the 12 things to do before the appraiser arrives?
1. Boost curb appeal
The exterior is the first thing I record. Trim shrubs back from the house, clear the walk and steps, repair broken railings or walkway trip hazards, and remove debris. Curb appeal will not move the market by itself, but visible neglect on the outside makes me look harder at what is behind the walls.
2. Tidy and declutter
I am not grading your housekeeping. But clutter hides things: closets, built-ins, damaged floors, water stains. An open, reasonably tidy house lets me see the finishes and measure accurately. Clear the stairs and the kitchen counters, and put the dog in a crate.
3. Make minor repairs
These small fixes are the ones that most often delay a closing, especially with FHA financing:
- missing or loose stair handrails
- exposed wiring, open junction boxes and missing outlet covers
- a water heater without a proper relief valve and discharge pipe
- missing or broken smoke alarms and carbon monoxide alarms
- chipping or peeling paint on a home built before 1978, a possible lead hazard that should be scraped, prepped and repainted using lead-safe work practices by a contractor who follows EPA rules (do not dry-sand it yourself)
My article 7 Red Flags That Delay FHA and Conventional Appraisals explains each one and what a typical fix looks like.
4. Ensure key systems work
Turn on the electricity, gas and water so I can observe the systems I am required to report. A working permanent heat source is expected, so have an older furnace or boiler serviced and test it before the visit. In a vacant or inherited house, call the utility companies a few days early and check the pilot light. Air conditioning is not required for FHA, but it does affect market value.
5. Check for water issues
A dripping roof, a damp basement wall, a leaking pipe or a wet crawlspace will be noted in the report. Fix active leaks beforehand. If a repair is not possible in time, be ready to explain what has been done, and consider a short written statement from a licensed roofer or plumber.
6. Verify accurate square footage
Size is one of the biggest value drivers, so I measure every home myself. Differences between what the county records show and what is actually there are common, especially with finished basements, enclosed porches and old additions. If you have a floor plan, a prior appraisal or a survey, have it available. I report what I measure and observe, and I have to explain any difference from public records.
7. Highlight recent updates
This is the most useful thing a homeowner can give me. List every improvement with a year and approximate cost: new roof, replacement windows, remodeled kitchen or bath, finished basement, new HVAC, added bedroom, deck, fence. Photos of the before and after help for work that is hidden, such as new wiring or plumbing.
8. Gather property documents
Have these ready:
- the sales contract (on a purchase the lender sends it; sellers can ask their agent to confirm)
- the ground rent status and, if it applies, the lease or registry information
- HOA or condominium fees and what they cover
- any survey or plat and information on a septic or well system
- a short list of truly comparable recent sales, if you know of any. I choose my own comparables and they have to be verified, so a stack of cherry-picked listings will not change anything, but a brief note about a sale I might otherwise miss is welcome.
9. Showcase energy efficiency
Efficiency features are part of what buyers pay for. Note new or high-efficiency windows, added insulation, a newer heat pump or furnace, a high-efficiency water heater, and any solar panels, along with installation dates. Owned and leased systems are treated differently, so bring the paperwork. I cover that in Solar Panels and Maryland Home Value
10. Confirm permits and compliance
If permits were pulled for an addition, finished basement, deck or major system replacement, bring the permit numbers. Unpermitted work can raise questions with the lender and the appraiser. If the home is a rental, have the Baltimore City rental license and any lead paint certificate handy.
11. Keep the home accessible
Unlock the basement, attic, utility room, garage, shed and any other building. Clear a path to the furnace, water heater and electrical panel, and make sure the lockbox or keys work. If I cannot get to an area, I cannot report it, and I may have to come back, which delays everything.
12. Present a clean, well-maintained home
Put it all together: clean, bright and in working order. You do not have to attend the appraisal, but if you do, show me through, answer questions honestly and let me work. Be candid about problems. I will find them anyway, and a straightforward owner builds more trust than a defensive one.
What does not matter much?
Save your money on these.
- Staging furniture and décor. Furnishings are not part of the real estate and I do not value them.
- Fresh flowers, scented candles and baking cookies. Pleasant, but irrelevant.
- Expensive cosmetic updates made only for the appraisal. A $15,000 kitchen refresh rarely returns $15,000 in value. If you are considering one, talk to a professional first. I wrote about this in How Much Is My Baltimore House Really Worth?
- Pressure. Telling an appraiser what the house "needs to appraise for" does not help your case, and appraisers are required to be independent.
Is the checklist different for buyers or sellers?
Mostly the same. As a seller you control the condition and the paperwork, so you carry more of the work. As a buyer, you generally do not control access, but you can ask your agent to make sure the seller has done items 3, 4 and 11. If the appraisal is for a refinance, you are in the seller's position.
Your one-page checklist
- ☐ Boost curb appeal
- ☐ Tidy and declutter
- ☐ Make minor repairs: handrails, wiring, relief valve, alarms, peeling paint
- ☐ Ensure key systems work: utilities on, heat and cooling running
- ☐ Check for water issues
- ☐ Verify accurate square footage
- ☐ Highlight recent updates, with years and costs
- ☐ Gather property documents: contract, ground rent, HOA, survey
- ☐ Showcase energy efficiency
- ☐ Confirm permits and compliance
- ☐ Keep the home accessible
- ☐ Present a clean, well-maintained home
Common questions
Will fixing things before the appraisal raise the value?
It depends. Repairing a safety defect can prevent a repair requirement and protect the deal. Cosmetic updates may add little. Condition is one of several factors in the analysis.
Should I clean the house?
Yes, reasonably. It helps me see accurately. No one expects perfection.
Do I need to give the appraiser my receipts?
You do not have to, but a simple list of upgrades with approximate years and costs is very helpful. Receipts and permits strengthen it.
Can I be there during the appraisal?
Yes. Many owners are. Just let the appraiser work and answer questions when asked.
What if I disagree with the appraisal result?
You may have options, including a reconsideration of value request through your lender. Read Can You Challenge a Low Home Appraisal in Baltimore? for the steps.
The bottom line
Preparation is about accuracy and speed, not about spin. Open the house, fix what is unsafe, document what you have improved, and be straightforward. Do that and you give the appraiser what they need to do the job properly, and you give your closing date its best chance. If you are curious how long the process will take, see How Long Does a Home Appraisal Take in Baltimore?
Want a second pair of eyes before the appraiser arrives? Call me and I will tell you what I would look at.
Sources
- HUD Single Family Housing Policy Handbook 4000.1
- HUD Mortgagee Letter 2022-11: Revised Appraisal Validity Periods
- Maryland SDAT: Real Property and Ground Rent Registry
This article is general information, not legal, tax or financial advice. All dollar examples are hypothetical and rules change, so confirm current requirements with your lender, a Maryland attorney, your CPA or a title company.